250K+Registered Accounts
18K+Concurrent Research Sessions
$4.2B+Processed Volume
120+Markets Worldwide
Kesnokravu Reviews — Real Analysts, Documented Findings
Laurent Beaumont
Fixed Income Analyst · Paris, France
The macro overlay linking Treasury yield curves to crypto correlation regimes offered a structured starting point for cross-asset scenario documentation. I could layer sovereign-rate context onto digital-asset positioning and see where the two narratives conflicted, which improved our weekly briefing accuracy.
Annika Strand
Quantitative Strategist · Stockholm, Sweden
Walk-forward evaluation and regime-segmented backtest reports made it straightforward to challenge headline win-rate figures before presenting them to the research committee. The ability to segment by volatility, trend, and liquidity conditions exposed several strategies that looked compelling only in favourable regimes.
Haruki Sato
Derivatives Researcher · Osaka, Japan
Funding-rate overlays, liquidation-pressure maps, and depth-of-book tracking created a cohesive workspace for examining short-horizon derivative setups during volatile sessions. Seeing the interaction between perpetual funding and spot order-book imbalance in a single view reduced the preparation time for each research note considerably.
Valentina Cruz
Portfolio Risk Manager · Buenos Aires, Argentina
The concentration heatmap across venues, protocols, and quote currencies exposed overlapping exposures our legacy spreadsheet model missed. Stress-test scenarios with correlated drawdowns, liquidity discounts, and withdrawal-delay assumptions helped the risk committee quantify tail exposures before approving new allocations.
Brendan Gallagher
Execution Technologist · Chicago, United States
Arrival-price benchmarks, participation-rate controls, and basis-point slippage decomposition gave our desk a reliable way to separate signal quality from execution quality. The latency dashboard distinguishing market-data delay from venue acknowledgement helped us identify infrastructure bottlenecks that a single average would have hidden.
Irina Petrova
Quantitative Analyst · Saint Petersburg, Russia
The confidence-calibration display showing model agreement alongside historical error rates provided genuine transparency rather than a decorative percentage. Being able to inspect which data streams supported or contradicted a scenario made the research output more defensible during peer review and compliance sign-off.
✓ Verified
Samuel Njoku
Market Data Engineer · Lagos
"Feed-quality dashboards with timestamp drift detection and gap analysis saved hours of manual reconciliation each week."★★★★★ 4.8/5
✓ Verified
Liesel Brandt
Research Director · Munich
"Regime-tagged pattern libraries and false-positive frequency tables replaced guesswork with structured hypothesis testing."★★★★★ 4.9/5
✓ Verified
Tomasz Kowalski
Systematic Trader · Warsaw
"Execution-cost decomposition separating spread, impact, delay, and funding made strategy evaluation far more realistic."★★★★★ 4.7/5
✓ Verified
Miriam Goldstein
Compliance Analyst · Tel Aviv
"Audit trails with decision timestamps and conflicting-evidence logs simplified our regulatory reporting obligations."★★★★★ 4.8/5
✓ Verified
Alejandro Ruiz
Day Trader · Bogotá
"Intraday drawdown limits, session timeouts, and consecutive-loss pauses kept my risk discipline intact during fast markets."★★★★★ 4.9/5
✓ Verified
Suki Watanabe
AI Research Lead · Kyoto
"Model-drift monitoring with feature-distribution comparisons and automatic confidence downgrades was genuinely forward-thinking."★★★★★ 4.8/5
Licensed and Supervised by
Trading strategies organised by execution horizon and risk profile
Sound trading research begins with temporal context. A pattern that drives a sub-minute scalp carries different weight for a position held across several weeks, and a macroeconomic regime shift central to swing analysis may inject only noise into an intraday execution decision. This framework separates scalping, day trading, and swing trading into independent analytical workflows. Each workflow pairs relevant market data, validation criteria, execution controls, and risk boundaries with the holding period it serves. The descriptions below illustrate how an analytical platform can structure information; they are not personalised recommendations, performance forecasts, or trading instructions.
Scalping: order-book surveillance and execution precision
- Latency: sub-2ms processing objective, with median, p95, and p99 reported independently.
- Order book: multi-level depth, imbalance ratio, cancellation velocity, and replenishment flow.
- Execution: spread capture, fill ratio, adverse-selection cost, and basis-point slippage.
- Controls: stale-feed rejection, maximum order participation, and automated circuit breakers.
Day trading: momentum validation across multiple horizons
- Momentum: relative volume, VWAP deviation, breadth, acceleration, and liquidation context.
- Validation: five-minute entry timing, fifteen-minute structural confirmation, and hourly regime filter.
- Risk sizing: volatility-scaled exposure, correlation caps, and predefined loss budgets.
- Session controls: drawdown halt, event calendar awareness, time-based exit, and end-of-session review.
Swing trading: macro synthesis and blockchain intelligence
- Macro layer: liquidity regime, DXY, real yields, equity correlation, and volatility environment.
- On-chain layer: exchange flows, cost-basis bands, active entities, and stablecoin supply.
- Entry protocol: confirmation, retest, continuation, and reserve allocation phases.
- Review cycle: daily risk check, weekly thesis reassessment, and event-driven invalidation.
Transforming raw information into transparent market context
The analytical engine is structured as three concurrent processing streams: language and sentiment analysis, macroeconomic surveillance, and neural pattern detection. No stream operates as an isolated oracle. All outputs carry timestamps, normalisation metadata, a confidence estimate, and cross-references to price and liquidity data before reaching the consolidated view. This architecture is designed to surface single-source bias and make inter-stream disagreement visible. A user can examine the evidence behind any score rather than receiving an opaque buy or sell label.
Multilingual news processing and sentiment extraction
- Coverage: NLP pipelines spanning 35+ languages with entity-level attribution.
- Noise controls: near-duplicate clustering, bot-activity detection, source scoring, and temporal decay.
- Outputs: event classification, novelty score, sentiment range, confidence, and affected asset mapping.
Macroeconomic surveillance and cross-asset linkages
- Rates: 2-year, 5-year, 10-year, and 30-year Treasury yields plus real-rate context.
- Risk gauges: DXY, VIX, equity indices, credit spreads, and commodity proxies.
- Statistics: rolling correlation, rank correlation, beta, downside capture, and lead-lag diagnostics.
Neural pattern detection and volume-profile analysis
- Library: 195+ price, candlestick, volatility, volume, and liquidity formations.
- Consensus: lower, middle, and higher-timeframe agreement with regime filters.
- Volume profile: value area, point of control, volume nodes, delta, and migration tracking.
Layered safeguards and measurable protection architecture
Encryption standard
The framework encrypts sensitive records at rest using authenticated AES-256-GCM and applies modern transport-layer encryption for data in motion. Unique nonces, managed key rotation, separation of duties, access logging, and hardware-backed key protection form integral parts of the control rather than optional enhancements. Encryption reduces exposure but does not substitute for secure identity management, endpoint hardening, or incident-response readiness.
Offline custody ratio
Ninety-five percent of custodial holdings are allocated to offline storage, with the online balance restricted to anticipated operational demand. Offline custody limits online attack surface while introducing its own governance, recovery, and key-management requirements.
Availability objective
The five-nines figure represents an architectural target, not a historically measured service-level record. Meaningful monitoring would need to specify excluded maintenance windows, regional failure scope, degraded-service definitions, API availability, and the measurement period. Resilience relies on redundant regions, health probes, tested failover, capacity headroom, backup restoration, and post-incident analysis. Public availability claims should be derived from independently reviewable telemetry.
Independent assessment cadence
The framework schedules an independent control assessment every quarter, supplemented by continuous vulnerability scanning and annual penetration testing. Assessment scope should encompass applications, infrastructure, identity, custody, vendors, and recovery. A cadence alone conveys little without findings, remediation timelines, retesting, assessor independence, and disclosure of material exceptions.
Liquid reserve
The liquid reserve backstops customer obligations and withdrawal demand across varying market-liquidity conditions.
Information-security management
ISO 27001 delivers a structured information-security management framework encompassing risk assessment, policy governance, ownership assignment, corrective action, and continual improvement cycles.
Payment-data scope
PCI DSS governs environments that store, process, or transmit payment-card data. Appropriate scope reduction, tokenisation, network segmentation, vulnerability management, access control, monitoring, and assessor evidence are all required. Certification of a payment provider does not automatically extend to every connected platform, so the responsible entity and covered data flows must be stated with precision.
Operational-effectiveness attestation
A SOC 2 Type II report evaluates whether described controls operated effectively throughout a defined review period. Marketing copy should not imply that the report is publicly accessible or applies to every service. Users should be informed of the reporting period, trust-service criteria, auditor identity, scope, complementary controls, exceptions, and access procedures before treating the label as evidence.
How raw observations become a reviewable decision record
Data provenance and normalisation
Every analytical claim traces back to its data source. The research pipeline records origin, timestamp, venue, symbol mapping, quote currency, precision, and collection status. Duplicate trades, crossed order books, implausible prices, missing intervals, chain reorganisations, and late macro revisions are flagged before any feature is calculated. Prices from separate venues are not merged naively: fee structure, quote currency, liquidity, and index methodology are preserved. Normalisation produces comparable inputs while retaining enough metadata for anomaly investigation. When coverage drops below a defined threshold, the system lowers confidence rather than filling gaps with an apparently precise estimate.
Feature engineering follows the same principle. Returns are adjusted for interval length, volume is compared with an asset-specific baseline, and extreme observations are winsorised only when the transformation is disclosed. On-chain series are aligned to confirmation time, not merely block labels. News timestamps distinguish publication, collection, and first market reaction. This creates an evidence trail any researcher can reproduce and prevents data cleaning from becoming an invisible source of favourable results.
Forward-looking validation without hindsight
Historical analysis can appear convincing when a model inadvertently accesses future data. The workflow employs chronological training, validation, and test partitions, then repeats evaluation through walk-forward windows. Fees, spread, estimated slippage, funding, and delayed execution are incorporated before a result is summarised. Parameters are selected on one period and evaluated on another. Multiple-testing corrections are applied when many formations or thresholds are compared, reducing the chance that random variation masquerades as discovery.
Results are segmented by trend state, volatility regime, liquidity tier, and macro context. The report includes sample size, uncertainty interval, drawdown, turnover, and failure periods alongside any favourable statistic. Benchmark comparisons separate market exposure from incremental signal value. Model changes receive version identifiers, approval records, and rollback criteria. These practices cannot prove a pattern will persist, but they make limitations visible and enable another researcher to challenge the assumptions.
Explainability and human oversight
A consolidated score is useful only when its components can be individually inspected. Each scenario therefore lists supporting and conflicting evidence: momentum, order-book state, macro conditions, sentiment, on-chain measures, pattern similarity, liquidity, and event risk. Confidence is calibrated against historical error rather than presented as a decorative percentage. When two streams disagree, the interface displays the conflict. A human reviewer can exclude a faulty source, append a note, or reject an output without rewriting the underlying record.
Decision logs capture the information available at the time, not a revised story assembled afterward. Reviewers can compare the original thesis with subsequent price path, execution assumptions, and invalidation events. This encourages learning from false positives and missed opportunities without converting research into a promise. Automated systems organise evidence at scale; responsibility for suitability, authorisation, and final action remains with the user and applicable regulated professionals.
Execution-cost decomposition
A strategy should be appraised after the costs required to express it. The research record separates explicit trading fees from spread, market impact, delay, funding, borrow cost, and opportunity cost from unfilled instructions. Arrival price establishes the observable benchmark at decision time. Volume-weighted and time-weighted reference prices help explain whether an execution was favourable relative to activity during the interval, but they do not erase constraints that existed at the decision timestamp.
Market impact is estimated as both temporary displacement and persistent price movement after an order. The estimate changes with participation rate, order-book depth, volatility, venue, and time of day. A large theoretical return can evaporate when realistic fill assumptions are applied, particularly in thinly traded assets. The platform therefore displays gross and net scenarios together. Sensitivity tables show what happens when fees, delay, or slippage exceed expectations. This prevents a research result from resting on one optimistic execution assumption.
Portfolio interaction and exposure mapping
An isolated signal can amplify risk already present elsewhere in a portfolio. The portfolio layer maps exposure by asset, sector, protocol dependency, quote currency, custody venue, liquidity tier, and common risk factor. Correlation matrices are combined with stress scenarios because correlations tend to rise during market disruption. Stablecoin exposure, wrapped assets, bridges, staking arrangements, and exchange balances are recorded separately rather than treated as equivalent cash.
Concentration controls can cap a single asset, a single venue, a single blockchain ecosystem, or a single underlying economic theme. Marginal contribution to risk shows how a proposed scenario changes total volatility and drawdown sensitivity. Stress tests apply price shocks, volatility expansion, correlation convergence, withdrawal delays, and liquidity discounts. These are hypothetical diagnostics, not forecasts. Their value lies in identifying hidden dependence before a market event makes it visible. The final record distinguishes diversification by label from diversification by actual risk behaviour.
Monitoring, model drift, and retirement
A deployed model can deteriorate even when its code remains unchanged. Input distributions shift, exchange mechanics evolve, new market participants alter behaviour, and relationships learned in one regime can weaken in another. Monitoring compares current feature distributions, confidence calibration, error rates, execution gaps, and source coverage with the development baseline. Alerts identify data drift, concept drift, abnormal missingness, and performance outside a defined tolerance.
Alerts trigger investigation rather than automatic causal claims. A model can be restricted, recalibrated, rolled back, or retired when evidence no longer supports its use. Shadow evaluation compares a replacement with the current version before promotion. Incident records document impact, response, correction, and lessons learned. Periodic governance reviews examine whether the model still serves its stated purpose and whether users understand its boundaries. Retirement is treated as a normal control, not a failure to be concealed. This lifecycle perspective is especially important in digital-asset markets, where infrastructure and market structure can change faster than a static historical study suggests.
Understanding technical metrics without overstated precision
Detailed terminology improves research only when every figure has a clear definition, observation window, and stated limitation. The following reference notes explain how the platform connects execution, signal, and risk metrics without presenting a dashboard value as a guaranteed outcome.
Latency, liquidity, and slippage
Latency is measured from a defined starting event to a defined completion event. Market-data latency, model-processing latency, order-transmission latency, venue acknowledgement, and fill completion answer different questions and should never be compressed into a single marketing number. A sub-2ms target may describe internal processing while network transit and venue response contribute additional time. Percentiles, measurement geography, hardware, load, and sample period must accompany the statistic.
Liquidity likewise depends on definition. Displayed depth can vanish, hidden orders can improve a fill, and volume reported by a venue may not represent executable capacity at the desired price. Slippage is therefore measured against a named benchmark and expressed in both currency and basis points. Researchers compare expected and realised values by asset, venue, order size, volatility, and session. A negative result is retained because excluding difficult fills would produce a misleading execution profile.
Confidence, consensus, and pattern counts
A confidence value does not equal the probability of profit unless it has been explicitly calibrated to that event, and even calibrated probabilities depend on the future resembling the evaluation sample. In this framework, confidence summarises evidence quality, model agreement, data completeness, and historical error within a stated regime. Multi-timeframe consensus means that independent horizon checks point in compatible directions; it does not mean that three correlated indicators provide three independent confirmations.
The library of 195+ formations describes the breadth of the taxonomy, not the number of active opportunities or the quality of every individual pattern. Closely related formations are grouped during validation, and each candidate must meet minimum sample and liquidity requirements. Users can inspect historical false positives, regime sensitivity, and invalidation rules. This distinction keeps a large pattern catalogue from becoming an unsupported claim of predictive power.
Security, reserves, and system availability
AES-256-GCM provides authenticated encryption, offline custody separates long-term holdings from online operational balances, and reserve management supports customer obligations and withdrawal demand.
A 99.999% availability objective is supported by redundant regions, health probes, capacity planning, backup restoration, and incident-response procedures.
Understanding Kesnokravu — Honest Answers to Essential Trading Questions
In-depth responses covering order execution, strategy workflows, technical indicators, account security, regulatory standing, platform comparisons, and funding requirements.
How does Kesnokravu convert raw market data into actionable research?
Kesnokravu integrates order-book depth, liquidity profiles, fill metrics, funding rates, exchange flows, whale movements, and blockchain analytics with standard technical tools. The analysis layer assesses trend state, momentum strength, breakout structure, support-resistance zones, moving-average alignment, RSI, MACD, Fibonacci levels, and volume distribution. Signals are validated across multiple timeframes rather than evaluated in isolation. The interface also surfaces contradictory evidence, source timestamps, data-completeness indicators, and model confidence. This structure enables users to examine why a scenario emerged and where it would become invalid. The output is research information, not a guaranteed prediction, personalised investment recommendation, or assurance that any particular entry, stop-loss, or take-profit level will succeed.
What factors determine order-fill speed on Kesnokravu?
The research architecture targets sub-2ms internal processing, but actual order fills are shaped by network distance, venue response time, order type, order-book liquidity, volatility, queue position, and requested size. The execution panel separates processing latency from transmission, acknowledgement, partial fills, and final completion. It reports median, p95, and p99 execution speed rather than relying on a single flattering average. Fill accuracy is evaluated against arrival price, expected spread, fees, and realised slippage. During thin liquidity or rapid price swings, fills may be delayed, partial, rejected, or completed at a worse price. The latency figure should therefore be understood as a system objective rather than a promise that every live order will execute within two milliseconds.
Can Kesnokravu support scalping and intraday research?
The workspace includes tools relevant to scalping and intraday research, including ultra-low-latency monitoring, level-two order-book tracking, spread analysis, liquidity-imbalance detection, slippage estimates, momentum signals, breakout validation, and intraday volume profiles. Scalping scenarios focus on execution speed, fill accuracy, participation rate, and adverse selection because small theoretical edges can vanish after costs. Intraday scenarios add multi-timeframe confirmation, moving averages, RSI, MACD, support-resistance mapping, funding-rate context, and adaptive position sizing. Users can define stop-loss, take-profit, time-exit, and maximum-drawdown conditions. These controls organise research but cannot eliminate volatility, technical outages, price gaps, liquidation risk, or the possibility of losing the entire amount committed to a trade.
How does the platform approach swing-trading analysis?
Swing-trading research connects daily and weekly trend structure with macroeconomic conditions and blockchain telemetry. The platform compares moving-average direction, momentum, breakout or retest behaviour, Fibonacci retracement zones, support-resistance levels, volume profile, and volatility regime. It can overlay Treasury yields, DXY, VIX, exchange flows, stablecoin liquidity, whale tracking, holder cost bands, and derivatives funding rates. A phased-entry protocol divides a scenario into confirmation, retest, continuation, and reserve stages, each with an allocation cap and invalidation rule. Position sizing reflects volatility, correlation, liquidity, and portfolio concentration. The workflow is designed for documented analysis over several days or weeks; it does not guarantee that a trend will persist or that a blockchain observation reveals a participant's intention.
Which charting tools and technical indicators are included?
The analytical workspace spans trend, momentum, volatility, liquidity, and market-structure tools. Researchers can compare simple and exponential moving averages, RSI, MACD, Fibonacci retracement and extension zones, breakout levels, support-resistance maps, volume profile, point of control, value areas, volume delta, and volatility bands. Order-book data adds bid-ask depth, imbalance ratios, spread tracking, cancellation velocity, and replenishment flow. Derivatives context includes funding rate and liquidation pressure, while on-chain analytics can include whale tracking and exchange flows. Indicators are evaluated across multiple timeframes and checked for agreement or conflict. No indicator is treated as a standalone instruction. Settings, sampling interval, transaction costs, and evolving market regimes can materially alter any historical relationship.
How are risk controls implemented on Kesnokravu?
Risk management begins with a maximum-loss budget rather than a desired return. The research model adjusts position sizing for volatility, entry-to-stop distance, liquidity, asset correlation, venue concentration, and existing portfolio exposure. Users can document stop-loss, take-profit, time-based exit, trailing invalidation, and maximum-drawdown rules before reviewing any scenario. The dashboard separates gross performance from fees, funding, spread, and slippage. It can report win rate, average win and loss, payoff ratio, Sharpe ratio, turnover, and worst historical drawdown during backtesting. These statistics describe a sample and may deteriorate under live conditions. Risk controls may reduce particular exposures, but they cannot eliminate market, counterparty, custody, operational, regulatory, or model risk.
Does Kesnokravu offer backtesting and performance analytics?
The research environment supports chronological backtesting with training, validation, and out-of-sample periods. Walk-forward evaluation reduces the risk of selecting parameters with hindsight, while transaction fees, spread, estimated slippage, funding, and execution delay are included before results are summarised. Reports can show win rate, payoff ratio, expectancy, Sharpe ratio, volatility, turnover, maximum drawdown, and sensitivity to worse execution assumptions. Results are segmented by trend state, volatility regime, liquidity tier, and macro context so a strategy is not judged from one unusually favourable period. Backtesting remains hypothetical: missing data, look-ahead bias, overfitting, venue changes, unavailable liquidity, and market impact can make live results materially different from a historical simulation.
What safeguards protect accounts on Kesnokravu?
Kesnokravu combines AES-256-GCM encryption for protected data at rest with encrypted transport, managed key rotation, access logging, separation of duties, and multi-factor authentication. The security architecture also includes offline custody, withdrawal controls, redundant infrastructure, backup restoration, external review, vulnerability scanning, and incident-response procedures. ISO 27001 provides an information-security management framework, PCI DSS covers payment-card data environments, and SOC 2 Type II addresses the operating effectiveness of controls over a review period. Together, these measures create layered protection across identity, application, infrastructure, custody, recovery, and operational monitoring. Automated anomaly detection, session controls, least-privilege permissions, backup testing, and continuous alerting strengthen protection throughout the account and data lifecycle.
What is Kesnokravu's regulatory standing?
Kesnokravu operates within the regulatory requirements applicable to its services, legal entities, products, custody model, customer locations, and supported jurisdictions. The platform's compliance framework covers customer onboarding, identity controls, transaction monitoring, record keeping, market-conduct procedures, operational resilience, custody governance, and risk disclosures. Its regulatory section identifies the CFTC, FCA, SEC, and ASIC as relevant financial-market authorities across major target regions. Service availability, product access, account features, and customer protections can vary by jurisdiction because financial and digital-asset rules differ between markets. Compliance teams maintain policies for sanctions screening, suspicious-activity escalation, customer communications, conflicts of interest, complaint handling, data retention, and periodic control reviews.
How should I compare Kesnokravu with alternative platforms?
Kesnokravu is positioned as an analytical workspace rather than a claim to be universally superior to every exchange, broker, charting package, or portfolio tool. Comparison should examine data coverage, order-book depth, execution speed, fill accuracy, slippage reporting, technical indicators, blockchain analytics, whale tracking, exchange flow, backtesting methodology, security evidence, pricing, support, and regulatory status. The platform emphasises explainability: users can see which data streams support or challenge a scenario and how fees or latency affect an estimated result. Competitors may offer deeper execution connectivity, different assets, lower costs, or stronger verified credentials. A fair evaluation should rely on current documentation and controlled testing rather than aggregated ratings, slogans, or historical results alone.
What funding is required to open an account?
The main platform page does not promote a fixed deposit amount because account requirements belong on the dedicated pricing page. Actual requirements may differ by region, account type, payment method, intermediary, currency, suitability rules, and current commercial terms. Before transferring funds, users should confirm the exact legal recipient, fee schedule, withdrawal process, custody arrangement, supported currency, refund policy, and whether a regulated provider is involved. A minimum deposit is not a recommended position size and should never override personal risk capacity. Position sizing should be based on an amount the user can afford to lose, the planned stop-loss distance, portfolio concentration, volatility, liquidity, and total drawdown limit. Never send funds solely because a webpage displays an urgency message.
Does Kesnokravu promise a profitable win rate?
No. Win rate is a historical or simulated statistic and does not guarantee profit. A strategy can win frequently and still lose money when average losses exceed average gains, while a lower win rate can coexist with positive expectancy when the payoff ratio is larger. Evaluation should consider fees, funding, slippage, latency, market impact, position sizing, maximum drawdown, Sharpe ratio, sample size, and the market regimes represented in backtesting. Live order fills may differ from simulated fills, and relationships can change as liquidity, participants, regulation, and technology evolve. Kesnokravu presents analytical context and risk controls, not assured returns. Users remain responsible for independent decisions and should seek appropriately authorised financial, legal, and tax advice where needed.
Risk disclosure
Essential information about digital-asset market risk
Digital-asset trading carries substantial risk and may result in partial or total loss of capital. Prices can move rapidly due to liquidity conditions, leverage, liquidation cascades, market concentration, protocol events, cyber incidents, regulatory announcements, operational failures, stablecoin dislocations, and broader economic developments. Historical performance, simulated results, backtests, pattern similarity, sentiment scores, and model confidence do not predict or guarantee future outcomes. Backtests can be affected by selection bias, look-ahead bias, overfitting, incomplete data, underestimated fees, unavailable liquidity, and execution assumptions that cannot be reproduced in live markets.
Platform analytics are provided for informational and research purposes. They do not constitute investment advice, a recommendation, an offer, solicitation, fiduciary service, tax guidance, or legal counsel. Terms such as signal, strategy, confidence, target, reserve, security, or institutional grade must be interpreted within their stated methodology.
Users remain responsible for assessing suitability, financial circumstances, knowledge, objectives, jurisdictional restrictions, and ability to bear loss. Leverage can magnify gains and losses and may create obligations beyond an initial margin amount. Stop orders can execute at worse prices or fail during gaps and outages. Diversification and risk controls may reduce certain exposures but cannot eliminate market, counterparty, custody, technology, or regulatory risk. Consider obtaining advice from appropriately authorised professionals and never commit funds required for essential expenses. Access to a platform or analytical tool does not imply regulatory approval, deposit insurance, asset protection, or guaranteed liquidity.
Kesnokravu
Start handel nu
Dansk
Opret din handelskonto
Opret din handelskonto
Udfyld formularen for at starte kontoopsætningen og udforske platformens værktøjer.
Kalibreret instrumentpanel til kryptomarkedet
Saml signaler, eksponeringsinstrumenter og guidet kontokalibrering i én afmålt visning, før du starter en protokolrådgivning.
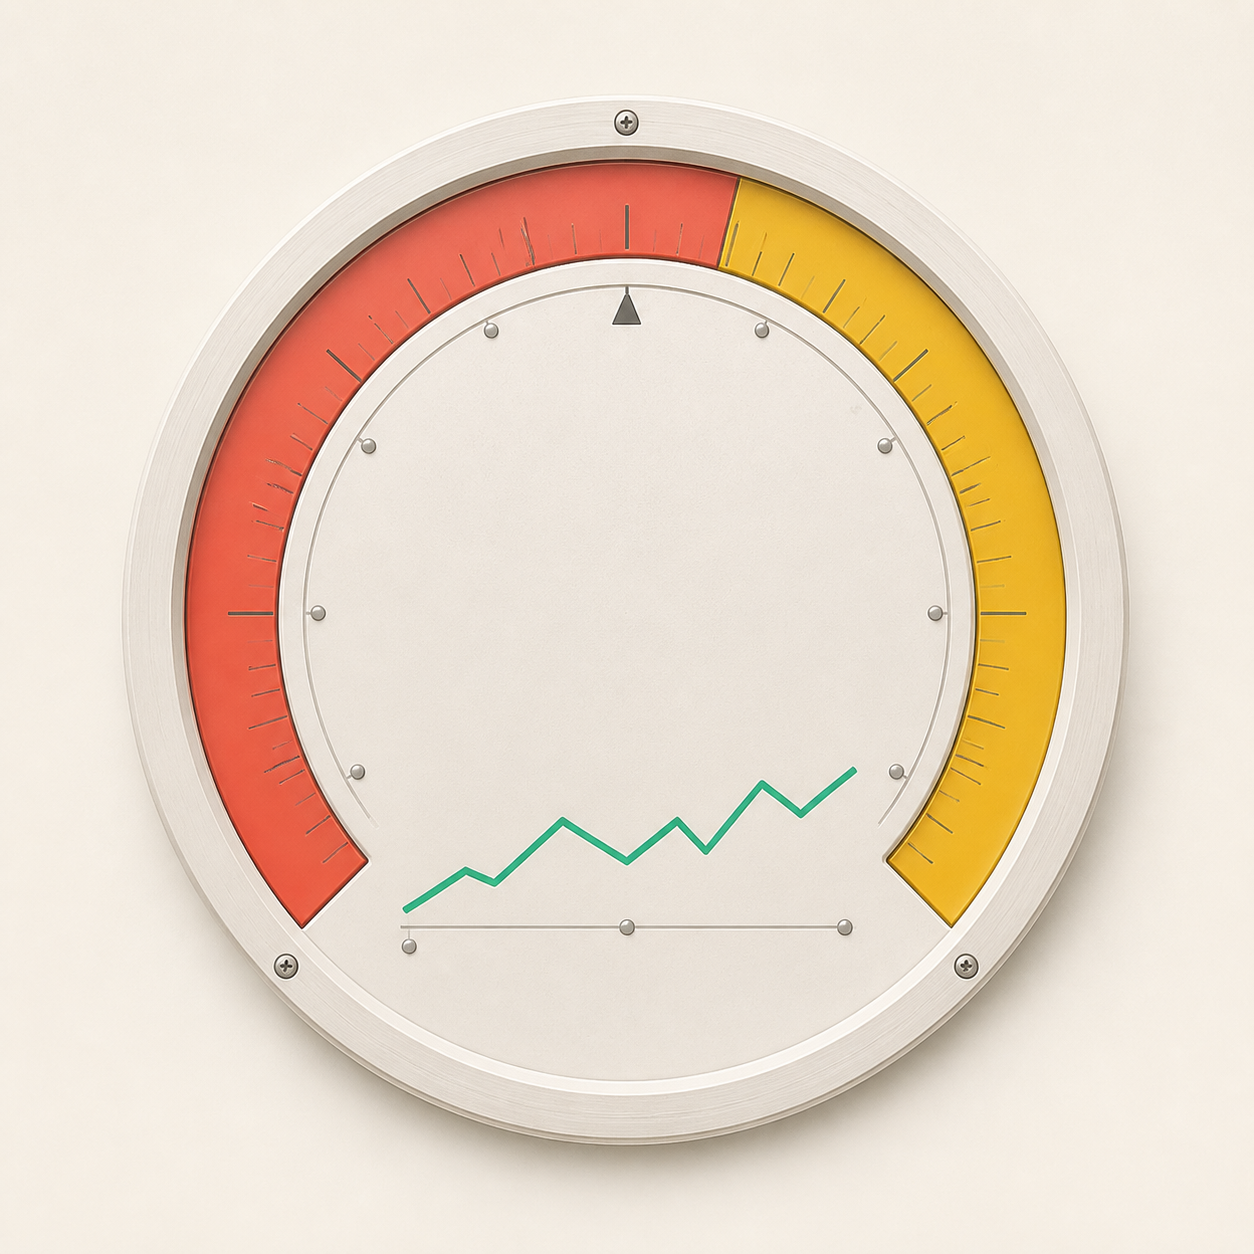
68/100
Trend
Momentum
Liquidity
Sentiment
250K+Markedsmålere
$4.2B+Porteføljeaflæsninger
99.99%Guidet kalibrering
4.8/5Tilbagemeldinger fra operatører
BTC/USDT 67,842.21 +1.72%ETH/USDT 3,241.65 +2.11%SOL/USDT 182.44 +3.09%BNB/USDT 592.10 +1.28%
BTC / USDT
67,842.21 +1.72% (24H)1H4H1D1W1M3M
24H VOL$32.1BMARKET CAP$1.34T24H CHANGE+1.79%HIGH (24H)$68,125LOW (24H)$66,102
Instrumentramme
Kalibrering af markedsmålere
Mål likviditet, volatilitet og momentum med kontekstuelle instrumenter på tværs af relevante tidsrum.
Eksponeringsaflæsning
Gennemgå fordeling, koncentration og mulige risikoindikatorer før en protokolsession.
Personlig kalibreringsvejledning
Del mål og kontaktoplysninger, så næste protokoltrin kan tilpasses dine behov.
En anmodningssekvens du kan gennemgå før indsendelse
Tydelige instrumentmærkater, synlige protokoltrin og lokal vejledning gør opstartssekvensen nem at følge.
Gør spredte markedsaflæsninger til en kalibreret briefing
Hvad Kesnokravu kalibrerer med sin porteføljeinstrumentprotokol
Momentum-målere
Præcisionsmålere måler pris- og momentumaflæsninger for at kalibrere din forståelse af trendstyrken.
On-chain-flowmålere
Dedikerede flowmålere kvantificerer on-chain-transaktionsvolumener for at levere kalibrerede aflæsninger af kapitalens migration.
Børsstrøm-instrumenter
Nettostrøminstrumenter på tværs af børser er justeret til at producere nøjagtige aflæsninger af akkumulerings- og distributionsfaser.
Hvalaktivitetssensorer
Højfølsomme sensorer overvåger store indehaveres wallet-bevægelser for at registrere signifikante positionsændringer med præcision.
Volatilitets- & sentimentskalaer
Dobbeltskala-instrumenter krydsreferencer frygt-grådighed-aflæsninger med volatilitetsmålinger for en kalibreret stressvurdering.
Risikokorrelationssonder
Korrelationssonder udsættes på tværs af aktivpar for at generere kalibrerede kort over porteføljeeksponeringens afhængigheder.
Protokolvej
01
02
03
Tre afmålte trin fra første aflæsning til en forberedt konsultation
Scan
Undersøg de aktuelle markedsinstrumenter og tilgængelige analytiske aflæsninger.
Kalibrer briefingen
Beskriv prioriteter, tilgængelig kapital og risicoparametre, du ønsker at drøfte.
Planlæg opfølgning
Del kontaktoplysninger, så teamet kan forberede en protokolkonform samtale.
FAQ
Praktiske spørgsmål før du starter en protokolkonsultation
01Hvad hjælper dette instrumentpanel mig med at gennemgå?
Det samler prismålere, markedssignaler, eksponeringsaflæsninger og onboarding-protokoller til en bedre afmålt samtale.
02Er det det samme som at handle på en børs?
Nej. Instrumentpanelet er lavet til analyse og forberedelse; ordrer og aktivtransaktioner udføres på en børs.
03Hvordan skal jeg forstå grafer og måleinstrumenter?
Brug dem som informative markedsinstrumenter. De viser en analyseprotokol og forudsiger eller garanterer ikke resultater.
04Kan en person med begrænset kryptoerfaring følge protokollen?
Ja. Indholdet er bygget op trin for trin med klare instrumentmærkater, der gør de vigtigste begreber tilgængelige.
05Hvad sker der, når jeg sender mine oplysninger?
Teamet kan gennemgå anmodningen, afklare prioriteter og forklare næste protokoltrin.
06Fjerner panelet investeringsrisikoen?
Nej. Markeder for digitale aktiver er fortsat volatile, og hver operatør skal selv vurdere risikoen før økonomiske beslutninger.